Financing Programs Explained: Types, Costs and Eligibility

A sofa that finally fits the room is sitting on the showroom floor, and the tag says $0 down. The old couch at home has a sag you feel every night. Rent is due, payday is next week, and the question is not whether the piece looks right. It is whether the payment still works after the tag comes off.
Why Financing Programs Matter for Your Furniture Budget
Friday's paycheck is already spoken for. Rent cleared, the truck needs gas, and the sofa you sat on still has to fit what is left. A low first payment does not answer that. The full price does.
Financing programs let you take furniture home now and pay over time. Deferred-interest promotions, equal-pay plans, lease-to-own, and no-credit-needed financing do not price the same purchase the same way. Each one changes the dollars you will end up paying, not just the first receipt.
Price every option in total dollars first. Then set that monthly payment next to the cash left after rent, food, and gas. If the payment fails that test, do not apply.
We are a family-owned store in Grants Pass, serving Medford, Ashland, and the Rogue Valley. Sit on the piece in our showroom before a payment plan starts. Comfort should be settled before the math is.
By the end you can put a total-dollar price on the program in front of you and say whether the monthly payment fits your household cash flow.
Four Financing Programs Compared Side by Side
The same furniture purchase can end with four different totals. Match the offer to the way you can pay, then add up every scheduled payment before you apply. Our dealership financing options page gives you a place to review the store's programs.
| Program | How it works | Cost to watch | Best for |
|---|---|---|---|
| Deferred-interest | Interest accrues from purchase and is waived only if the full balance is paid by the deadline | Any remaining balance can trigger accrued interest | Buyers who can clear the balance before the deadline |
| Equal-pay | Price is split into fixed monthly installments at 0% APR | Late fees may apply if a payment is missed; check whether the 0% APR has an end date | Buyers with steady monthly cash flow |
| Lease-to-own | Recurring rental payments; ownership transfers at the end or through an early-purchase option | Paying through the full term can cost more than buying outright; check the early-purchase terms | Buyers who need furniture now and cannot get approved for traditional credit |
| No-credit-needed financing | Approval is based on income and other checks rather than a credit score | Rates, fees, and total cost may exceed credit-based options; get the total in writing | New movers and buyers building credit |
The question that sorts them
Choose based on your payoff plan: can you clear a balance by a deadline, make fixed payments on schedule, or pay over time until you own the furniture? The first option puts the risk on a leftover balance. Equal-pay plans depend on making each installment on time. With lease-to-own, the total depends on the payment term and any early-purchase option.
Before signing, ask for three figures or terms:
- Total on-schedule cost: What will you pay in all if every payment is on time?
- A late or missed payment: What fee, rate change, or loss of the promotion follows?
- The kind of zero: Is the offer deferred interest, or a 0% APR with no end date?
Price the offer in dollars, not just by its monthly payment. Divide the total scheduled cost across the payment period, then compare that amount with the money left in your household budget after regular bills. If the payment leaves too little room for other expenses, choose a less expensive purchase or wait. A low payment does not make a high total affordable.
Gates Easy Pay is one option to compare alongside these programs. It offers $0 down with 6 equal payments, interest-free if paid in full within the promotional period, as well as no-credit-needed and lease-to-own options. Review the full terms before deciding which payment structure fits your budget.
Use the table to narrow your choices, then rule out any offer whose total cost or monthly payment does not fit.
How Deferred-Interest and Equal-Pay Plans Really Cost
Take a $2,400 sofa on a six-month deferred-interest promotion. Clearing it on time takes $400 a month. That is simple division, and it is the number that matters.
Interest starts accruing on the purchase date even when you are not billed for it yet. Pay $2,300 by month six and the leftover $100 can pull the accrued interest onto the balance. The Consumer Financial Protection Bureau credit card market report found that average retail APRs on private-label credit cards exceeded 31% at the end of 2024. At that rate, a small leftover is not a small problem.
Minimum payments versus a real payoff
A shopper who sends only the contractual minimum often still owes a large residual when the promotion ends. That residual can arrive with capitalized interest. The tag said no interest. The statement does not.
Equal-pay plans work differently. The price is split into fixed installments that carry no interest when every payment lands on time. The main risk is a late fee, not a surprise lump of back interest. Confirm in writing that the APR is 0%, not a waiver that expires.
Borrowers comparing fixed loans outside a store promotion can review installment credit examples for bad-credit borrowers to see how a set payment and a set term are supposed to look.
For Gates Easy Pay, calculate a payoff target above the contractual minimum, and keep deferred-interest promotions separate from genuine 0% APR installment loans. Our no-interest furniture financing notes spell out the six-payment structure so you can match it to this math.
Run these three checks in order:
- Find the promotion end date in writing.
- Divide the balance by the months left. That result is the full-payoff payment.
- Set autopay above the minimum, and put a reminder two weeks before the deadline.
Practical rule: A disclosure should show the end date, the payoff payment, the post-promotion APR, and whether new purchases follow different terms.
If any of those four items is missing, do not treat the offer as free money.
How Lease-to-Own and No-Credit-Needed Plans Really Cost
A sofa advertised for a small weekly payment may cost far more over the full agreement. Lease-to-own is a rental: you pay on a schedule, and ownership transfers only when the agreement's terms are met. An early-purchase option may let you own the item sooner, with a fee.
The term changes both the installment and the total. An FTC economic analysis of a major rent-to-own provider found that full-term lease payments in 2019 cost approximately twice the item's retail price. In that same 2019 analysis, a 90-day purchase option cost less than completing the full term, but added a $49 or $79 fee.
Three figures, side by side
Before comparing a weekly ad with a cash price, ask for the total cost under each ownership option. Our rent-to-own living room sets are easier to assess when you have the figures in writing.
| Figure | What to request | Why it matters |
|---|---|---|
| Cash price | Retail price of the sofa or mattress before financing | Sets the baseline for comparison |
| Total under early-purchase option | All payments made plus the buyout fee | Shows what owning sooner will cost |
| Total if every scheduled payment is made | Sum of every scheduled rental or installment payment | Shows the cost of completing the full term |
No-credit-needed financing may use income and other checks instead of a credit score. That can help people who are building credit or have recently moved, but rates and fees may be higher than with credit-based options. Compare the same three totals before deciding.
A manageable weekly payment can still add up to twice the cash price if you complete the full term.
Read the contract for the details that determine your actual cost:
- Ownership timing: Confirm when the sofa or mattress becomes yours.
- Late-payment consequences: Check the fees, default terms, and whether one missed payment affects the agreement.
- Return and repossession terms: Find out what happens if you stop paying or return the item.
- Fees inside the payment: Confirm whether delivery, protection plans, and other charges are included or billed separately.
Then test the payment against your household budget. Add any extra charges to the scheduled payments and calculate the full amount you would pay. If that total does not fit, compare a different term or program before applying.
Budget Examples for Southern Oregon Households
Say a Medford renter takes home $3,200 a month and wants that $2,400 sofa. The monthly figure only helps after you see the duration and the payoff risk on the same row.
| Scenario | Monthly payment | Duration | Payoff risk |
|---|---|---|---|
| Deferred-interest, paid in full by deadline | $400 | 6 months | Any balance left at the deadline accrues deferred interest at the post-promotion APR |
| Six equal payments with $0 down (Gates Easy Pay structure) | $400 | 6 months | A missed payment may trigger a late fee; confirm terms in writing |
| Equal-pay over 12 months at 0% APR | $200 | 12 months | Lower payment but a longer period in which a missed payment can cause a fee |
| Lease-to-own, full scheduled term | Full-term total near $4,800 on this sofa; installment only after the provider prints the schedule | The contract's full lease term | Total may approach twice the retail price |
| Lease-to-own, early-purchase option | Cash price plus a $49 or $79 fee in the 2019 90-day example; confirm this piece in writing | 90 days in that example | Fee added to buy out early; ask for the exact amount |
Three households, three calendars
The Medford renter can clear $400 for six months only if rent, utilities, and groceries are already covered. A 12-month equal-pay plan at $200 leaves more room and keeps the obligation on the calendar twice as long.
A Central Point new mover buying a $1,200 mattress set on six payments owes $200 a month. That is easier to place beside a first rent check than a $400 sofa payment. Bedroom sets in that range sit with our affordable bedroom furniture sets.
A Grants Pass retiree on a fixed income should want the lowest payment that still ends within the year. A tiny weekly lease that runs far past month twelve can cost more than a $200 equal-pay plan that is done in twelve months.
When the due date hits before payday
Timing creates the damage, not the interest rate alone. A draft that lands before payday, or on top of rent, can trigger an overdraft or nonsufficient-funds fee. The Federal Reserve's report on household well-being and credit found that 38% of buy now, pay later users who were charged a late-payment fee also experienced an overdraft or NSF fee.
List every active obligation on one calendar. Place each due date against your pay dates. Keep the new payment inside what remains after rent, utilities, and essentials.
The smallest monthly payment is not always the safest choice.
How to Qualify and Apply Step by Step
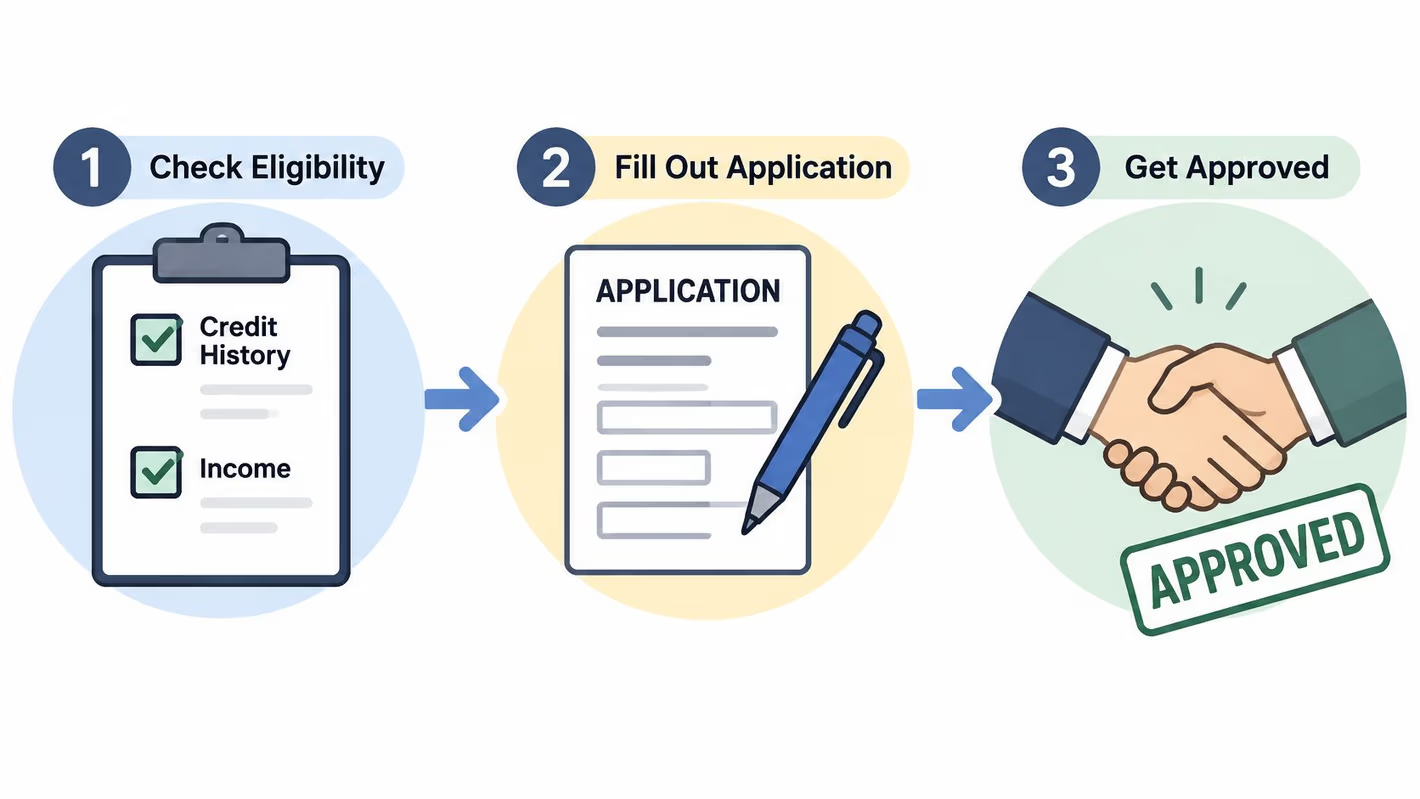
Each program checks different things. Deferred-interest and equal-pay offers usually weigh credit history. No-credit-needed plans consider income and other checks, while lease-to-own approval follows the provider's rental criteria. Choose a program only after comparing its total cost with the payment schedule your household can manage.
The Federal Reserve's 2024 household economic well-being report found that 34% of U.S. adults applied for some type of credit that year, and one-third of applicants were denied or approved for less than requested. Expect some applications to be declined. If approval is uncertain, a smaller first purchase can keep the monthly commitment manageable.
The application, in order
- Gather proof of identity and income, your address, bank details, and a list of recurring bills. Missing income documentation can slow a no-credit-needed application.
- Compare the proposed payment with your budget and pay dates before choosing a program. The payment should fit your cash flow when it comes due.
- Ask for the total cost and full payment schedule in writing before you apply. Compare what you will pay overall, not just the advertised monthly amount.
- Apply online or at our Grants Pass showroom. Gates Easy Pay applications are completed online. For details on financing without a credit check, review the available information before applying.
- Read the disclosure closely. Check the promotional end date, payment amount, post-promotion APR, late fees, and any included fees.
- Put each due date on your calendar and set reminders. Autopay can help keep a payment from slipping during a busy week.
- Once approved, confirm the delivery date and ask what to expect from professional in-home delivery, including assembly and setup.
If an application is declined, ask what factor affected the decision. Then consider a smaller purchase or another program, and compare the full cost and payment schedule before applying again.
Financing Questions Answered
Does $0 down mean you owe nothing? The purchase is still financed. Each scheduled payment goes toward the total, and skipping a payment at the start does not reduce the amount owed.
What does no-credit-needed mean for approval? The provider still reviews the application. Check the program's terms for what information it considers and what payments it requires before agreeing.
What happens if you miss a payment? You may owe a late fee. Review the payment terms before signing so you know what a missed due date could cost.
Can you pay off early? Ask whether early payoff or an early-purchase option carries a fee. Get the answer in writing and confirm it in the disclosure before sending extra money.
Does a deferred-interest offer equal 0% APR? Check the earlier deferred-interest explanation and compare the payoff deadline with the amount you can afford each month. A shorter deadline gives you less room to adjust if your budget changes.
Which program should you start with? Write down the total cost and payment schedule for each option, then check whether the monthly amount fits your household cash flow. Bring those figures to our Grants Pass showroom, where a design consultant can help match the terms to the furniture you're considering.
Choose the Program That Fits Your Monthly Budget
Price every option in total dollars first. Then ask whether that month's payment still fits the household after rent, groceries, and the rest of the bills. Apply only if both answers hold.
Deferred interest fits when you can clear the full balance before the deadline, so the amount you pay stays the ticket price. Put the payoff date on the calendar the day you sign.
Equal pay fits when you want a fixed schedule at a true 0% APR. Divide the price by the number of payments, including a plan with $0 down and six equal payments. If that monthly figure crowds out the rest of the month, pick a smaller piece or wait.
Lease-to-own or no-credit-needed financing fits only when approval is the barrier. Get the total you will pay, the monthly amount, and any early-purchase fee in writing. A smaller payment is the wrong program when the total runs well past what the furniture is worth to you.
Fold in the extras before you judge the payment. Gates Sleep Care belongs on a mattress purchase. Gates Care Shield belongs if you want coverage for accidental spills and tears. Both change the total.
Sit on the sofa or recliner from La-Z-Boy, Flexsteel, Ashley, or Beautyrest, and have a design consultant write the schedule and the total on paper. We will match a lower price on Flexsteel, Beautyrest, La-Z-Boy, or Ashley furniture offered in the Grants Pass, Ashland, or Medford area. If the payment does not fit your cash flow, we will tell you to pass.
A tighter budget still has room in Unique Finds: reclaimed wood, teak, and one-of-a-kind pieces.
Bring the monthly number you can fund and visit Gates Home Furnishings in Grants Pass, or browse the collection online.